Car Finance in Southampton: A Practical Guide for Buyers
10 November 2026
Southampton is a city that rewards having your own transport. Between the commute along the M27, the school run across Shirley or Bitterne, the trip to the docks or the airport, and the weekend escape into the New Forest, a reliable car makes daily life considerably easier. Public transport covers a lot of the city centre well, but it doesn't always stretch to shift work, out-of-town retail parks or visiting family across Hampshire.
For many people, buying outright isn't realistic. That's where car finance comes in — and where a lot of confusion, and a fair amount of worry, tends to sit. This guide explains how car credit in Southampton generally works, what lenders look at, and how to approach an application calmly and sensibly.
Ready to see what you could borrow?
Apply online with RightDrive Car Finance in a few minutes.
What car finance actually is
Car finance is simply borrowing to buy a vehicle, then repaying over an agreed term with interest. The two arrangements you'll come across most often are:
Hire Purchase (HP). You pay a deposit (sometimes none), then fixed monthly payments across a term — commonly two to five years. The vehicle belongs to the lender until the final payment, after which it becomes yours. HP is straightforward and popular with used-car buyers because there's no balloon payment waiting at the end.
Personal Contract Purchase (PCP). Monthly payments are often lower because part of the car's value is deferred to a larger optional final payment. At the end you can pay that sum and keep the car, hand it back, or part-exchange. PCP usually comes with mileage limits and condition expectations, so it suits predictable, moderate mileage more than it suits long motorway commutes.
There are also unsecured personal loans from banks and credit unions, which let you own the car from day one. These can work well if your credit profile is strong, but approval tends to be less flexible than specialist motor finance.
How applications are assessed
It's worth saying plainly: no responsible broker or lender can promise approval before an application is assessed, and you should treat any claim of "guaranteed" finance or "no credit check" lending with caution. Every regulated lender must check that borrowing is affordable for you.
What they typically consider:
- Your credit history. Payment behaviour on previous and current credit, including any defaults, County Court Judgments or arrangements. Age and recency matter — a missed payment from five years ago weighs less than one from last month.
- Affordability. Your income against your regular outgoings: rent or mortgage, household bills, childcare, existing credit commitments. Lenders want to see headroom, not a budget stretched to its limit.
- Stability. Time in your current job and at your current address. Consistency is reassuring to an underwriter.
- The vehicle itself. Age, mileage and value all play a part, because the car is the security on the agreement.
If your credit record has some bruises, you are not automatically ruled out. A number of lenders specialise in exactly those circumstances and look at the fuller picture rather than a single score. Rates in that part of the market are generally higher, reflecting the additional risk, and a deposit may strengthen the application. But the door is not closed.
Cars you could drive away in
See all our cars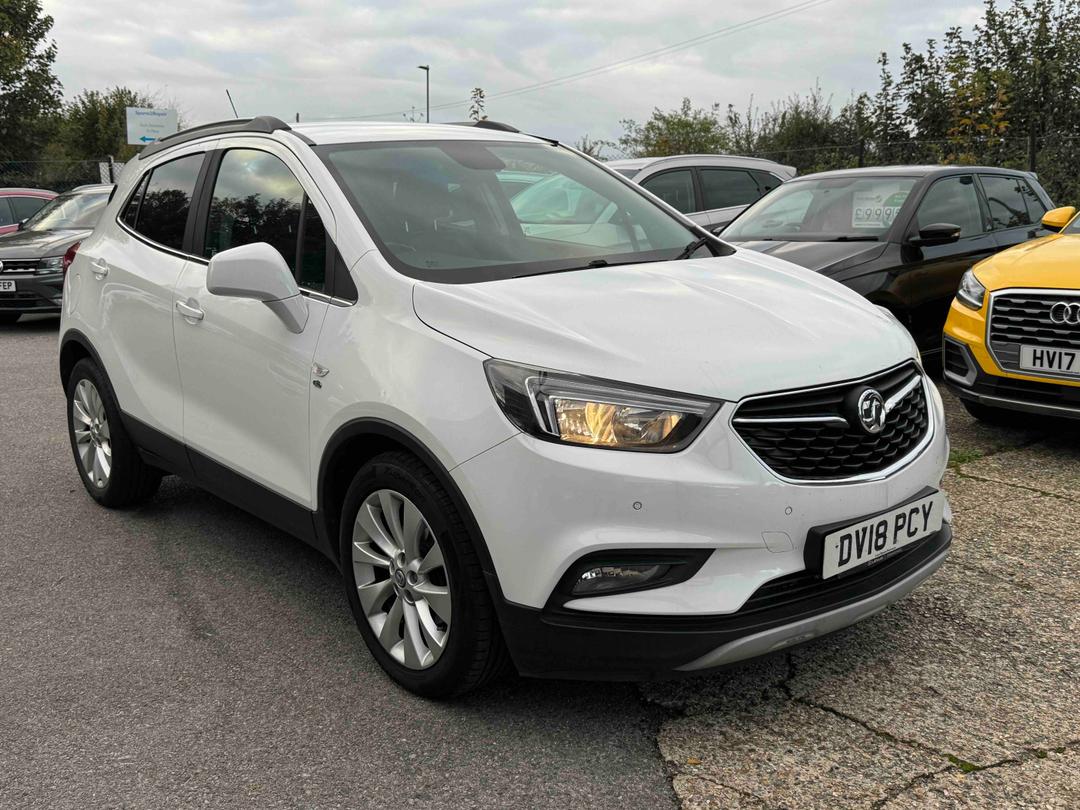
Preparing before you apply
A little groundwork makes the whole process smoother and reduces the chance of unwelcome surprises.
Check your own credit file first. You can access your report free through the main credit reference agencies. Look for errors — an account you've settled still showing as open, an address that isn't yours, a default recorded incorrectly. These can be disputed and corrected.
Get on the electoral roll. Being registered at your current Southampton address helps lenders verify who you are and where you live. It's a small administrative step with a disproportionate benefit.
Work out your real monthly budget. Not just the finance payment. Insurance in some SO postcodes can be meaningful, and you'll need to allow for fuel or charging, road tax, servicing, MOT and a sensible contingency for tyres and repairs. A car that looks affordable on the monthly figure alone can become stressful once the running costs land.
Gather your paperwork. Typically that means photo ID, proof of address, recent payslips or accounts if you're self-employed, and bank statements covering the last few months.
How it works
- 1
Apply online
Tell us about yourself and the car you are after. It only takes a few minutes.
- 2
Get your decision
We look through the lenders we work with to find the one that suits you.
- 3
Drive away
Choose your car from our stock to fit your budget, and we get you on the road.
Choosing the right car for Southampton driving
The vehicle matters as much as the finance. Think honestly about how you'll actually use it.
If you're mostly driving short distances around Portswood, Woolston or Millbrook, a small petrol or hybrid is usually the sensible choice — lower running costs, easier parking, cheaper insurance. If you're commuting out towards Winchester, Eastleigh or along the coast, comfort and economy at motorway speeds become more important.
Southampton also has a Clean Air Zone affecting certain vehicle types, so if you're considering an older diesel, it's worth checking current rules and charges for the category of vehicle you're looking at before you commit.
Finally, be realistic about size. A larger car is tempting, but it costs more to insure, more to fuel and more to park in a city with plenty of narrow residential streets.
Working with a broker
A credit broker doesn't lend money itself. It submits your details to a panel of lenders and tries to match your circumstances to one likely to say yes on fair terms. The advantage is that you avoid making multiple separate applications — repeated hard searches in a short space of time can make your file look stretched.
When you're comparing options for car credit in Southampton, check that the business is authorised and regulated by the Financial Conduct Authority, ask how it is paid, and ask whether an initial check is a soft search. You should also be given the total amount repayable, not just a monthly figure — that's the number that tells you what the agreement really costs.
What our customers say
Read all our reviews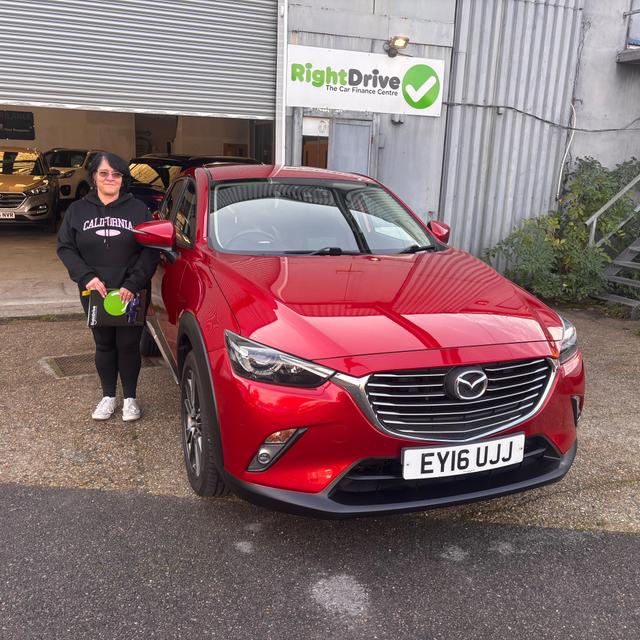
I found the team very helpful. They are very polite and had me driving away in minutes. Thank you RightDrive!
Paula G.

Very polite and helpful!
Paige P.
Walked in - finance was straight away sorted. Nina was a great help and friendly.
Thomas S.
A word on expectations
If your credit history isn't perfect, it's natural to expect judgement. In practice, a good dealership treats it as information, not character assessment. Life events — illness, redundancy, separation — show up on credit files all the time, and underwriters see them daily.
What helps is honesty. Give accurate figures, declare existing commitments, and don't overstate income. An application built on realistic numbers is more likely to be approved and, crucially, more likely to be comfortable to live with for the next three or four years.
Take your time, compare properly, and choose the agreement you can maintain on a difficult month — not just an easy one.
Car finance calculator
See roughly what a car could cost you each month.
A guide only, your own rate depends on your circumstances. Representative example: borrowing £7,500 over 48 months at 25.4% APR representative (25.4% fixed annual rate), 48 monthly payments of £239.77, total cost of credit £4,008.96, total amount payable £11,508.96.
Not sure if you are eligible?
See what lenders look for before you apply.
About RightDrive Car Finance
Car Finance Made Simple
5.0 from 41 reviews
PO16 9DR